UK Tax Rates and Allowances 2026/27 and 2027/28
Tax rates and allowances taken from the UK Government's website, including the Budget 2026 rates annex.
UK personal tax rates, thresholds and allowances for the current tax year (2026/27), the two preceding years, and the 2027/28 figures announced at the Budget on 28 October 2026. Figures apply to England, Wales and Northern Ireland; Scottish income tax bands differ, and Scotland's 2027/28 rates will be set in the Scottish Budget on 3 December 2026.
| 2027/28 (announced) | 2026/27 | 2025/26 | 2024/25 | |
|---|---|---|---|---|
| Income Tax — Bands & Rates | ||||
| Basic rate (20%) — taxable income up to | £37,700 | £37,700 | £37,700 | £37,700 |
| Higher rate (40%) — applies above | £37,700 | £37,700 | £37,700 | £37,700 |
| Additional rate (45%) — applies above | £125,140 | £125,140 | £125,140 | £125,140 |
| Higher rate threshold (with full personal allowance) | £50,270 | £50,270 | £50,270 | £50,270 |
| Personal Allowances & Reliefs | ||||
| Personal allowance | £12,570 | £12,570 | £12,570 | £12,570 |
| Personal allowance taper begins at | £100,000 | £100,000 | £100,000 | £100,000 |
| Personal allowance fully withdrawn at | £125,140 | £125,140 | £125,140 | £125,140 |
| Marriage allowance (transferable) | £1,260 | £1,260 | £1,260 | £1,260 |
| Blind person's allowance | £3,370 | £3,250 | £3,130 | £3,070 |
| Rent-a-room relief | £7,500† | £7,500 | £7,500 | £7,500 |
| Trading allowance | £1,000† | £1,000 | £1,000 | £1,000 |
| Property allowance | £1,000† | £1,000 | £1,000 | £1,000 |
| Property income rate — basic / higher / additional | 24% / 44% / 49% | 20% / 40% / 45% | 20% / 40% / 45% | 20% / 40% / 45% |
| Savings Income | ||||
| Personal savings allowance — basic rate | £1,000 | £1,000 | £1,000 | £1,000 |
| Personal savings allowance — higher rate | £500 | £500 | £500 | £500 |
| Personal savings allowance — additional rate | £0† | £0 | £0 | £0 |
| Starting rate for savings (0%) — up to | £5,000 | £5,000 | £5,000 | £5,000 |
| Savings rate — basic rate | 24% | 20% | 20% | 20% |
| Savings rate — higher rate | 44% | 40% | 40% | 40% |
| Savings rate — additional rate | 49% | 45% | 45% | 45% |
| Dividend Income | ||||
| Dividend allowance | £500 | £500 | £500 | £500 |
| Ordinary (basic) rate | 10.75% | 10.75% | 8.75% | 8.75% |
| Upper (higher) rate | 35.75% | 35.75% | 33.75% | 33.75% |
| Additional rate | 39.35% | 39.35% | 39.35% | 39.35% |
| Capital Gains Tax | ||||
| Annual exempt amount (individuals) | £3,000 | £3,000 | £3,000 | £3,000 |
| Annual exempt amount (most trustees) | £1,500 | £1,500 | £1,500 | £1,500 |
| Rate on shares/other assets — basic rate taxpayer | 18% | 18% | 18% | 10% / 18%* |
| Rate on shares/other assets — higher/additional rate | 24% | 24% | 24% | 20% / 24%* |
| Rate on residential property — basic rate | 18% | 18% | 18% | 18% |
| Rate on residential property — higher/additional rate | 24% | 24% | 24% | 24% |
| Business Asset Disposal Relief — rate | 18% | 18% | 14% | 10% |
| Business Asset Disposal Relief — lifetime limit | £500,000 | £1,000,000 | £1,000,000 | £1,000,000 |
| Inheritance Tax | ||||
| Nil-rate band | £325,000 | £325,000 | £325,000 | £325,000 |
| Residence nil-rate band | £175,000 | £175,000 | £175,000 | £175,000 |
| Residence nil-rate band taper threshold | £2,000,000 | £2,000,000 | £2,000,000 | £2,000,000 |
| Standard rate on death | 40% | 40% | 40% | 40% |
| Reduced rate (10%+ to charity) | 36% | 36% | 36% | 36% |
| Lifetime rate on chargeable transfers | 20% | 20% | 20% | 20% |
| 100% business and agricultural property relief allowance | £2,500,000 | £2,500,000 | No limit | No limit |
| Annual gifting exemption | £3,000† | £3,000 | £3,000 | £3,000 |
| Small gifts exemption (per recipient) | £250† | £250 | £250 | £250 |
| Wedding gift to a child | £5,000† | £5,000 | £5,000 | £5,000 |
| Wedding gift to a grandchild | £2,500† | £2,500 | £2,500 | £2,500 |
| Wedding gift to anyone else | £1,000† | £1,000 | £1,000 | £1,000 |
| ISAs | ||||
| Overall ISA allowance | £20,000 | £20,000 | £20,000 | £20,000 |
| Cash ISA limit (all ages) | £20,000 | £20,000 | £20,000 | £20,000 |
| Junior ISA allowance | £9,000 | £9,000 | £9,000 | £9,000 |
| Lifetime ISA — maximum contribution | £4,000† | £4,000 | £4,000 | £4,000 |
| Pensions | ||||
| Annual allowance (standard) | £60,000 | £60,000 | £60,000 | £60,000 |
| Money purchase annual allowance | £10,000 | £10,000 | £10,000 | £10,000 |
| Tapered annual allowance — minimum | £10,000† | £10,000 | £10,000 | £10,000 |
| Adjusted income — taper begins | £260,000 | £260,000 | £260,000 | £260,000 |
| Threshold income — taper applies above | £200,000† | £200,000 | £200,000 | £200,000 |
| National Insurance — Employees (Class 1) | ||||
| Primary threshold (weekly) | £242 | £242 | £242 | £242 |
| Upper earnings limit (weekly) | £967 | £967 | £967 | £967 |
| Main rate (between PT and UEL) | 8% | 8% | 8% | 8% |
| Rate above upper earnings limit | 2% | 2% | 2% | 2% |
| National Insurance — Employers | ||||
| Secondary threshold (weekly) | £96 | £96 | £96 | £175 |
| Employer rate | 15% | 15% | 15% | 13.8% |
| National Insurance — Self-employed | ||||
| Class 2 — voluntary flat rate (weekly) | £3.80 | £3.65 | £3.50 | £3.45 |
| Class 4 — main rate | 6% | 6% | 6% | 6% |
| Class 4 — rate above upper profits limit | 2% | 2% | 2% | 2% |
*For 2024/25, CGT rates on shares and non-residential assets changed mid-year. Disposals before 30 October 2024 used 10% / 20%; disposals from 30 October 2024 used 18% / 24%.
Personal allowance reduces by £1 for every £2 of adjusted net income over £100,000. Dividend basic and higher rates increased by 2 percentage points from 6 April 2026. From 6 April 2026, Agricultural and Business Property Relief is capped: 100% relief on the first £2.5m of combined assets per person, 50% above.
About the 2027/28 column: these figures were announced at the Budget on 28 October 2026 and take effect from 6 April 2027, subject to legislation. From 6 April 2027, savings income and property income have their own tax rates, 4 percentage points above the main rates. The planned £12,000 cash ISA limit for under-65s has been scrapped: the cash ISA limit stays at £20,000 for everyone. Figures marked † are not listed in the Budget rates annex; no change to them has been announced. I'll confirm the column once the figures are final. For a plain-English summary of what's changing, see tax changes from April 2027. Information for general reference only — not financial or tax advice.
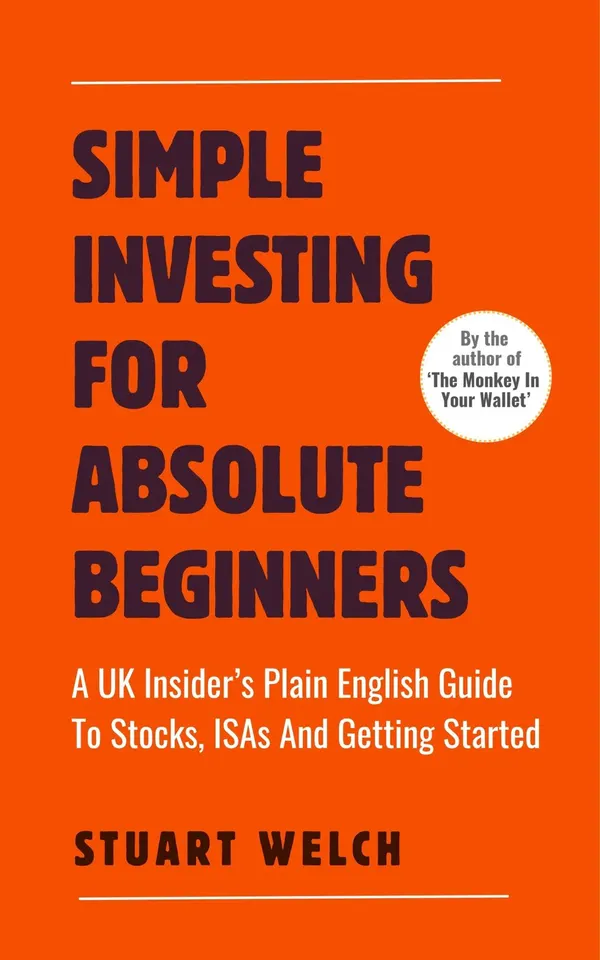
Simple Investing for Absolute Beginners
“Everything you need to know. Nothing you don't. In one afternoon.”
“The author clearly knows this world inside out, but writes like he's talking to a reasonable adult who just hasn't got round to it yet. … If you've been meaning to sort your finances out "at some point," this is the nudge that actually works.”Mrs Carolyn Fortune, Amazon review
Recommended reading on this topic
Full list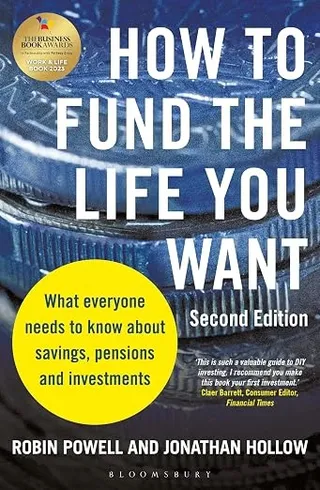
How to Fund the Life You Want
Robin Powell & Jonathan Hollow
A UK-specific guide to savings, pensions and investing by a financial journalist and a former Money and Pensions Service insider. Plain-spoken about how the industry profits from complexity.
View on AmazonBeyond the 4% Rule
Abraham Okusanya
One of the few books on retirement income written for UK retirees: how much you can safely draw from your pot. Best read once retirement is in sight.
View on Amazon